Debt Recycling: Turning Home Equity into Tax‑Efficient Investments
Bharat Finance Editorial Team · Published 13 June 2026 · Updated 13 June 2026
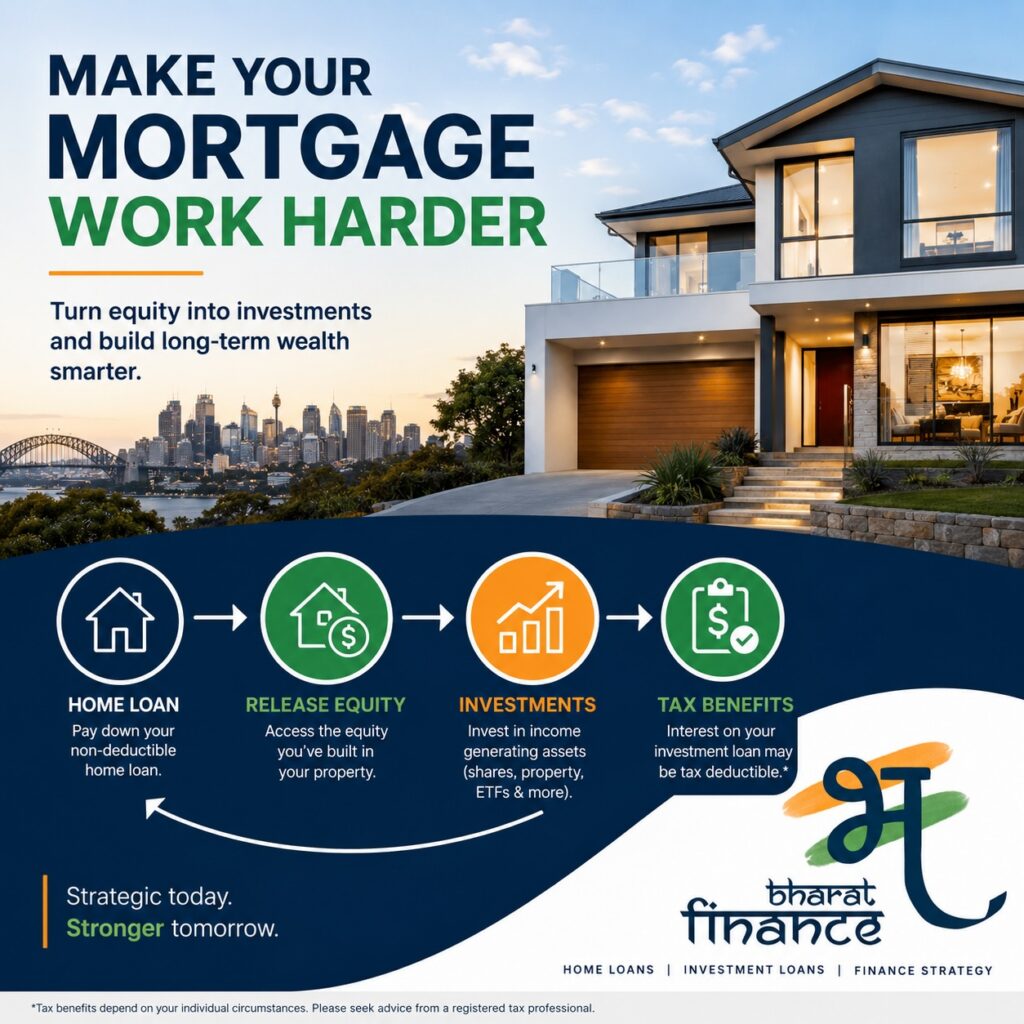
Debt recycling is a strategy used by homeowners to convert non‑deductible mortgage debt into tax‑deductible investment debt. The concept involves paying down your home loan and then re‑borrowing the freed‑up equity to invest in income‑producing assets . Over time, this shifts the composition of your debt from personal to investment purposes.
How it works
- Build equity: Make extra repayments or deposit surplus funds into an offset account to reduce the principal .
- Access equity: Use a redraw facility or separate loan to extract the equity you’ve created.
- Invest: Deploy the borrowed funds into assets such as shares, managed funds or investment property. Interest on this investment loan may be tax deductible .
- Reinvest returns: Use dividends or rental income to further reduce your home loan or reinvest, accelerating the recycling process.
- Repeat: As your equity grows, you can continue the cycle until your non‑deductible mortgage is replaced by investment debt.
Benefits
- Potential wealth creation: Investing borrowed funds in growth assets offers an opportunity to build wealth faster than simply paying down a mortgage.
- Tax efficiency: Interest on investment loans is generally tax deductible, which can improve after‑tax returns .
- Accelerated mortgage payoff: The strategy motivates regular extra repayments, which reduce non‑deductible debt more quickly.
Risks
- Market volatility: Investment returns are not guaranteed. A market downturn could reduce your portfolio’s value and leave you owing more than your assets are worth .
- Rising interest rates: Higher rates increase borrowing costs and can erode the benefit of tax deductions .
- Increased debt: You’re taking on more leverage; if you lack discipline, you could accumulate more debt than you can manage .
- Complex structuring: Improperly structured loans may jeopardise tax deductibility. Professional advice is essential .
Debt recycling is best suited to investors with stable incomes, a long time horizon and a high tolerance for risk. Always consult a tax adviser and financial planner before implementing this strategy.