How Much Can I Borrow? Understanding the 28/36 Rule in Australia
Bharat Finance Editorial Team · Published 26 April 2026 · Updated 27 April 2026
One of the first questions Australians ask before buying property is:
“How much can I actually borrow?”
Most people assume the answer depends only on income.
It doesn’t.
Lenders assess:
- your income,
- existing debts,
- living expenses,
- credit commitments,
- dependents,
- and future interest rate buffers.
That is why two people earning the same salary can end up with completely different borrowing capacities.
One of the most common lending benchmarks used globally – including concepts reflected in Australian servicing assessments – is the 28/36 rule.
Understanding this rule can help you:
- avoid overcommitting,
- prepare properly,
- and maximise your borrowing power strategically.
What Is the 28/36 Rule?
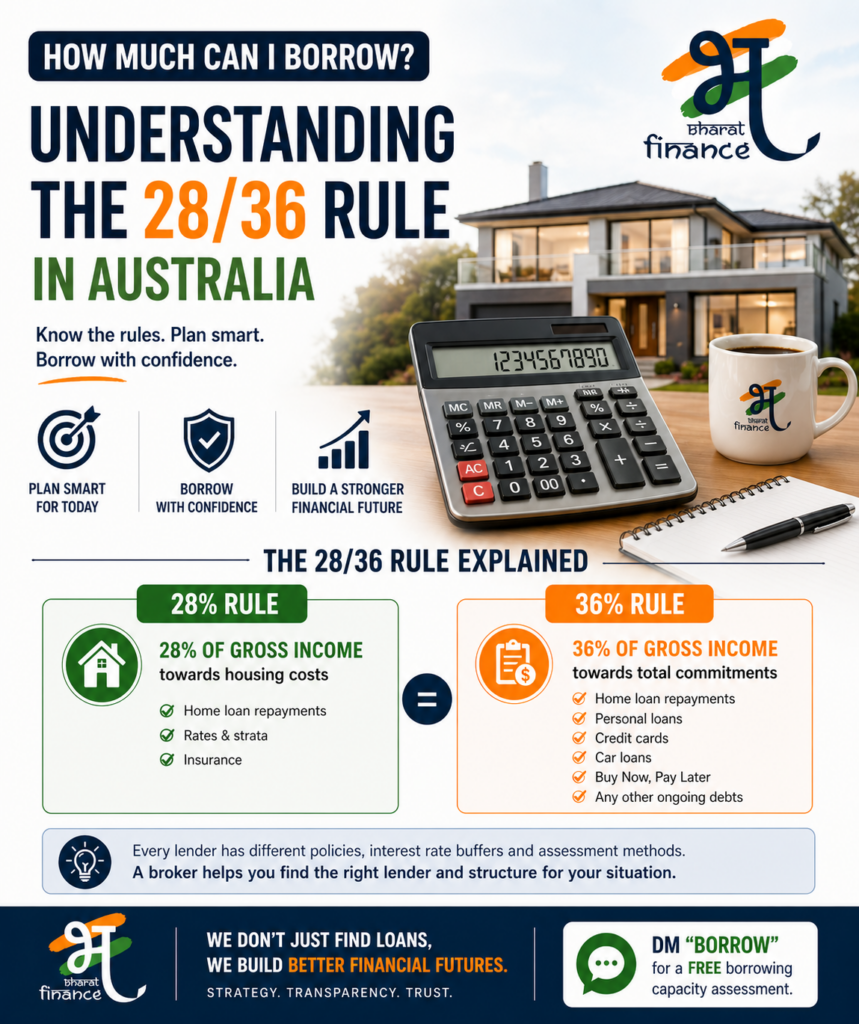
The 28/36 rule is a lending guideline used to assess whether a borrower can comfortably manage repayments.
It breaks borrowing into two parts:
28% Rule
No more than 28% of your gross income should go toward housing-related costs.
This includes:
- home loan repayments,
- interest,
- rates,
- strata,
- and home insurance.
36% Rule
No more than 36% of your gross income should go toward total debt commitments.
This includes:
- mortgage repayments,
- personal loans,
- car loans,
- credit cards,
- HECS/HELP debts,
- and Buy Now Pay Later commitments.
This helps lenders determine whether a borrower is financially stretched.
Does Australia Actually Use the 28/36 Rule?
Not exactly in a strict formula sense like the US.
Australian lenders use more advanced servicing models.
However, the principle behind the 28/36 rule still strongly applies:
lenders want to see that borrowers can comfortably afford repayments without financial stress.
In Australia, lenders also apply:
- interest rate buffers,
- living expense benchmarks,
- and stress testing.
That means your borrowing capacity is often lower than what you think it should be.
Why Borrowing Capacity Matters More Than Interest Rates
This is where many buyers get caught.
People obsess over:
“What interest rate can I get?”
But the smarter question is:
“How do I maximise my borrowing power strategically?”
Because borrowing capacity determines:
- what suburbs you can buy in,
- whether you can invest again later,
- and how scalable your property strategy becomes.
Poor loan structure today can reduce future opportunities significantly.
Example: How the 28/36 Rule Works
Let’s say:
- Household income = $150,000 per year
28% Rule
28% of gross income:
This means housing-related costs ideally remain around:
- $42,000 annually
- or about $3,500 per month
36% Rule
36% of gross income:
This means total debt obligations ideally remain around:
- $54,000 annually
- or about $4,500 per month
What Reduces Your Borrowing Capacity?
Many Australians unknowingly reduce their borrowing power through:
- large credit card limits,
- car finance,
- personal loans,
- HECS debt,
- excessive Buy Now Pay Later accounts,
- Private Health cover,
- Private education for kids,
- inconsistent income,
- or poor account conduct.
Even unused credit card limits can impact servicing.
This is one of the biggest reasons strategic planning matters before applying for a loan.
How Brokers Help Maximise Borrowing Capacity
Different lenders assess borrowers differently.
Some lenders are:
- more generous with overtime,
- better for self-employed borrowers,
- more investor-friendly,
- or more flexible with rental income.
That is why borrowing capacity can vary dramatically between lenders.
At Bharat Finance, the goal is not simply getting a loan approved.
The focus is:
- structuring finance properly,
- protecting future borrowing ability,
- and aligning lending with long-term wealth creation.
The Biggest Mistake Buyers Make
The biggest mistake is borrowing at their absolute maximum limit without strategy.
Just because a bank approves a certain amount does not mean it is financially comfortable long term.
Smart borrowers leave room for:
- rate increases,
- future investments,
- lifestyle flexibility,
- and emergency buffers.
Final Thoughts
Borrowing capacity is not just a number.
It is the foundation of your:
- property strategy,
- cash flow,
- future investments,
- and financial flexibility.
Understanding how lenders assess servicing can help you make smarter decisions before entering the market.
And in many cases, the right strategy can improve borrowing power significantly.
Speak With Bharat Finance
At Bharat Finance, we help Australians:
- understand their true borrowing capacity,
- compare multiple lenders,
- structure loans strategically,
- and plan for long-term wealth creation.
📩 DM “BORROW” for a free borrowing capacity assessment.